Parent company vs holding company is mainly a comparison of purpose and activity. Both can control subsidiaries, but a holding company primarily holds ownership interests or assets, while a parent company may also operate a business and direct group strategy.
Key Takeaways
- Parent companies and holding companies overlap because either may own or control subsidiaries.
- A pure holding company primarily owns companies or assets and does not conduct ordinary business operations.
- An operating parent company conducts business of its own while controlling one or more subsidiaries.
- Each subsidiary normally remains a separate legal entity with its own obligations, records, and governance.
- Dividends, service fees, loans, and asset transactions can move value within the group, subject to agreements and applicable law.
- Tax savings are not automatic and depend on entity type, ownership, elections, transactions, and jurisdiction.
Parent Company vs Holding Company: The Core Difference
A parent company is a business that owns or otherwise controls one or more subsidiary companies. It may conduct its own operations, sell products or services, employ workers, and actively coordinate the businesses it controls. A company can become a parent by forming a new subsidiary or acquiring control of an existing business.
The common holding company definition is narrower. A pure holding company exists primarily to own stock, membership interests, intellectual property, real estate, equipment, or other assets. It generally does not sell ordinary products or services. Its operating subsidiaries conduct the group's customer-facing business.
The terms are still sometimes used interchangeably because a holding company is also a parent when it controls subsidiaries. The practical difference between a parent company and a holding company is usually the owner's primary function, not a unique business-entity classification. A corporation or LLC may serve as either, subject to ownership and tax restrictions.
A mixed holding company further blurs the distinction. It owns subsidiaries but also operates a business. That makes it both a holding company in the broad sense and an operating parent company. When reviewing a real organization, look beyond its name. Examine what it owns, what activities it performs, how it earns revenue, and how much authority it exercises over each subsidiary.
Holding Company vs Parent Company Comparison
| Issue | Holding Company | Parent Company |
|---|---|---|
| Primary purpose | Hold companies, investments, or valuable assets | Own or control subsidiaries while potentially operating its own business |
| Operating activity | A pure holding company has little or no ordinary operating activity | May sell goods or services and employ operating personnel |
| Subsidiary ownership | May own all or a controlling interest in subsidiaries | May own all or a controlling interest in subsidiaries |
| Management role | Often focuses on capital allocation, major approvals, and ownership oversight | May coordinate strategy, branding, personnel, or shared operations |
| Revenue sources | May receive dividends, interest, rent, royalties, sale proceeds, or service payments | May receive operating revenue as well as returns or payments from subsidiaries |
| Common uses | Separate assets, hold multiple investments, and organize distinct operating businesses | Expand an operating business, acquire companies, or create specialized divisions |
| Potential drawbacks | Additional entities, filings, accounting, contracts, and administrative costs | More operational coordination and possible disputes over authority or resource allocation |
The label alone does not determine legal responsibility or tax treatment. Courts, tax authorities, lenders, and counterparties may examine ownership, governing documents, actual conduct, guarantees, and transactions between the companies. A business called a holding company can still create operational exposure if it signs contracts, employs operating staff, or directly participates in a subsidiary's activities.
Likewise, forming a parent does not automatically centralize every decision. A subsidiary's board, managers, or officers continue to exercise the authority given to them by applicable law and the company's governing documents. The parent-subsidiary relationship should therefore be documented rather than inferred from a corporate chart.
How Holding Companies and Subsidiaries Fit Together
A subsidiary is a separate legal entity controlled by another company. A wholly owned subsidiary has one parent owner. A parent can also exercise control without owning every share or membership interest, depending on voting rights, board appointment rights, and the governing documents.
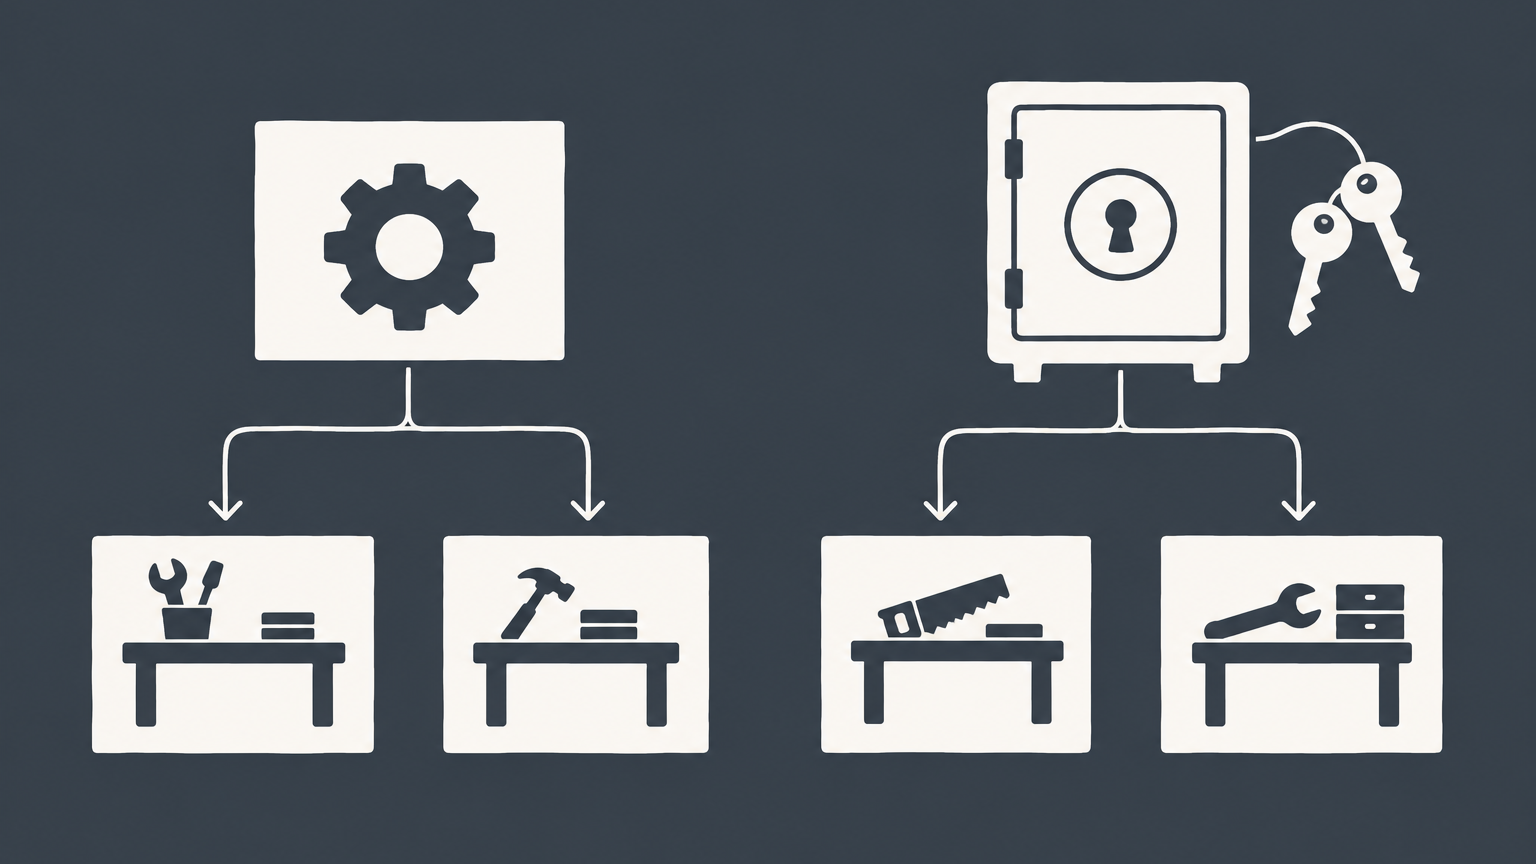
A simple operating-parent structure may look like this:
- Operating Parent: Runs its own business and owns Subsidiary A and Subsidiary B.
- Subsidiary A: Handles a product line, location, or specialized service.
- Subsidiary B: Handles a different product line, location, or specialized service.
A pure holding-company structure may look like this:
- Holding Company: Owns equity interests and approves major group decisions.
- Operating Company A: Contracts with customers and conducts one business.
- Operating Company B: Contracts with customers and conducts another business.
- Asset Company: May own specified real estate, equipment, or intellectual property used under written agreements.
These arrangements can make it easier to track results, admit investors into a particular venture, or sell one subsidiary without selling the entire group. They do not create absolute protection. The companies must maintain appropriate records, follow their governing documents, properly approve transactions, and avoid treating separate accounts and assets as if they belonged to one undivided business.
Control, Payments, and Intercompany Documents
Ownership establishes the corporate relationship, but documents and actual practices determine how a parent holding company works from day to day. The parent may reserve authority over budgets, executive appointments, major borrowing, acquisitions, asset sales, or distributions. Subsidiary managers may retain authority over ordinary operations within approved limits.
Value can move through the group in several ways. A subsidiary may declare dividends or distributions when permitted by its governing law and financial condition. One company may lend funds to another, purchase assets, license intellectual property, lease property, or pay for accounting, technology, legal, human-resources, or management services. These payments are not interchangeable. Each has distinct approval, documentation, accounting, and tax consequences.
Founders should decide and record:
- Which entity owns each subsidiary and asset.
- Who appoints managers, directors, and officers.
- Which decisions require parent or investor approval.
- How shared services are priced, provided, and documented.
- When subsidiaries may retain cash or make distributions.
- How loans, capital contributions, and asset transfers are approved.
- Which company employs personnel and signs third-party contracts.
Operating agreements, bylaws, shareholder agreements, board resolutions, service agreements, licenses, leases, and loan documents may all matter. Informal transfers or unclear responsibilities can undermine accounting, create owner disputes, and make it harder to show that each entity functions separately.
Parent Company vs Holding Company Taxes and Liability
A holding company does pay taxes when applicable to its classification, income, transactions, and jurisdiction. Creating one does not produce an automatic deduction, exemption, or lower rate. Federal treatment can depend on whether an entity is taxed as a corporation, partnership, or disregarded entity, as well as the character of income it receives.
Some affiliated corporate groups may elect to file consolidated federal income tax returns if they satisfy detailed ownership and eligibility requirements. The rules generally involve a common parent and at least 80 percent ownership by vote and value, but exclusions and additional requirements apply. Review current IRS guidance for corporations and obtain advice for the specific group before relying on consolidated treatment.
Entity eligibility also matters. An S corporation cannot have a corporation or partnership as a shareholder, and only specified individuals, estates, trusts, and tax-exempt organizations qualify. A proposed structure involving an S corporation requires careful review of the direct and indirect owners. See the separate discussion of whether a holding company can own an S corporation.
For liability, ownership alone usually does not resolve the issue. Separate entities generally have separate obligations, but facts such as guarantees, direct misconduct, contract language, agency, inadequate separation, or other legal doctrines can change the outcome. A parent may also voluntarily guarantee a subsidiary's debt. Review parent company and subsidiary liability before assuming that a corporate chart eliminates risk.
Types and Examples of Parent and Holding Structures
Examples of parent and subsidiary companies are easiest to understand through functions rather than brand names. Assume a regional construction company creates separate subsidiaries for commercial projects, residential projects, and equipment ownership. If the original construction company continues serving customers while controlling those subsidiaries, it is an operating parent.
If the owners instead form a new company that only holds the interests in those three businesses, the new entity is a pure holding company. The subsidiaries employ workers, sign customer contracts, and perform construction. The holding company focuses on ownership, financing decisions, and major approvals.
Common structural descriptions include:
- Pure holding company: Primarily owns companies or assets without conducting ordinary operations.
- Mixed holding company: Owns subsidiaries and conducts its own operating business.
- Immediate holding company: Directly owns a particular subsidiary but may itself be owned by another company.
- Intermediate holding company: Sits between an ultimate parent and lower-tier subsidiaries.
- Conglomerate parent: Controls businesses operating in different industries or markets.
A sister company is different. Sister companies share a parent but do not own one another. Their common ownership may allow shared services or coordinated strategy, but each sister remains a separate entity. Identifying the exact ownership chain prevents confusion about voting rights, payment obligations, and which company must approve a transaction.
Is a Holding Company a Good Idea for Your Business?
A holding company may be useful when you own multiple operating businesses, want different investors in separate ventures, plan to acquire or sell business units, or need a deliberate system for owning valuable assets. A parent structure may fit better when an existing operating business is expanding through new subsidiaries and should continue directing group operations.
The disadvantages can outweigh the benefits for a small business with limited assets and one straightforward operation. Every added entity can bring formation expenses, annual filings, accounting work, bank accounts, governance records, contracts, tax analysis, and state compliance. Separating assets also requires properly documented transfers, and lender consent or third-party approval may be necessary.
Before deciding, compare the expected risk and growth benefits against the continuing administrative burden. Consider where each company will operate, which entity will employ people, how intellectual property will be used, who will receive revenue, and how owners will access cash. State selection should follow business needs and current requirements rather than assumptions that one jurisdiction is universally best.
If you are choosing entities, transferring assets or ownership interests, or defining control and payments across several companies, you can post your legal need on UpCounsel's marketplace. An attorney can design the ownership structure, draft governance and intercompany agreements, and review liability, tax, and state-law implications with appropriate tax professionals. Responses typically arrive within a day.
How to Set Up a Parent or Holding Company
Start with a written ownership chart. Identify the ultimate owners, proposed parent, each subsidiary, ownership percentages, voting rights, and the location of major assets. Then choose the entity type for each company based on management, investment, liability, and tax needs. A holding company is a function, so forming an LLC or corporation does not by itself complete the structure.
Formation commonly involves filing organizational documents under state law, adopting governing documents, issuing ownership interests, appointing decision-makers, and establishing records and accounts. The parent must then acquire or receive the subsidiary interests. Existing businesses may require purchase agreements, contribution documents, assignments, valuations, consents, and updated ownership records.
After formation, implement the relationship in practice. Keep separate financial records and accounts. Use the correct company name on contracts and invoices. Approve major transactions under each entity's governing rules. Put services, loans, licenses, leases, and asset transfers in writing. Review insurance coverage and confirm who employs staff and owns work product.
For a more detailed sequence, see how to create a holding company. If the operating business will remain at the top of the structure, review the steps for creating a parent company. Before filing, check each relevant state's current instructions and coordinate legal decisions with tax and accounting advice.
Frequently Asked Questions
What Is a Parent Company?
A parent company is an entity that owns or controls at least one other legally separate business. Control can arise through voting equity, contractual rights, or authority over the subsidiary's governing body. The parent may be an active operating business, and its level of involvement can range from approving major decisions to coordinating strategy across the group.
Is a Holding Company the Same as a Parent Company?
A holding company can be a parent company, but the terms are not always identical. A pure holding company primarily holds companies or assets, while an operating parent also conducts its own business. Some organizations use the labels loosely, so ownership records, activities, and governance authority provide a more reliable answer than the company's name.
Does a Holding Company Pay Taxes?
Yes, a holding company may have federal, state, local, or foreign tax obligations. The result depends on its entity classification, elections, income, deductions, ownership, and locations. Even an entity with no current income may have filing or reporting duties. Tax treatment should be modeled before forming the company or moving assets into it.
Can a Subsidiary Be Liable for a Parent Company?
Yes, a subsidiary can face exposure in some circumstances, but common ownership alone does not automatically make it responsible for the parent's debts. Exposure may arise from a guarantee, a joint contract, the subsidiary's own conduct, an asset transfer, or facts supporting another legal theory. The governing law and transaction documents will control the analysis.
Do Subsidiaries Pay the Parent Company?
Subsidiaries may pay a parent company when a valid distribution, service arrangement, loan, lease, license, or asset transaction supports the payment. A parent cannot simply withdraw subsidiary funds without considering approvals, solvency restrictions, contracts, minority-owner rights, and tax rules. Written policies help distinguish lawful payments from undocumented transfers.
Can a Corporation Be a Holding Company?
Yes, a corporation can function as a holding company by owning companies, investments, or other assets. An LLC may also serve that function. The better entity choice depends on the owners, financing plans, desired governance, subsidiary types, and tax treatment. Special ownership rules, including S corporation shareholder restrictions, can limit a proposed arrangement.


